Annual capex across energy, compute, and industry has gone from $2 trillion to $6 trillion in five years. Most of that money is landing in Asia.
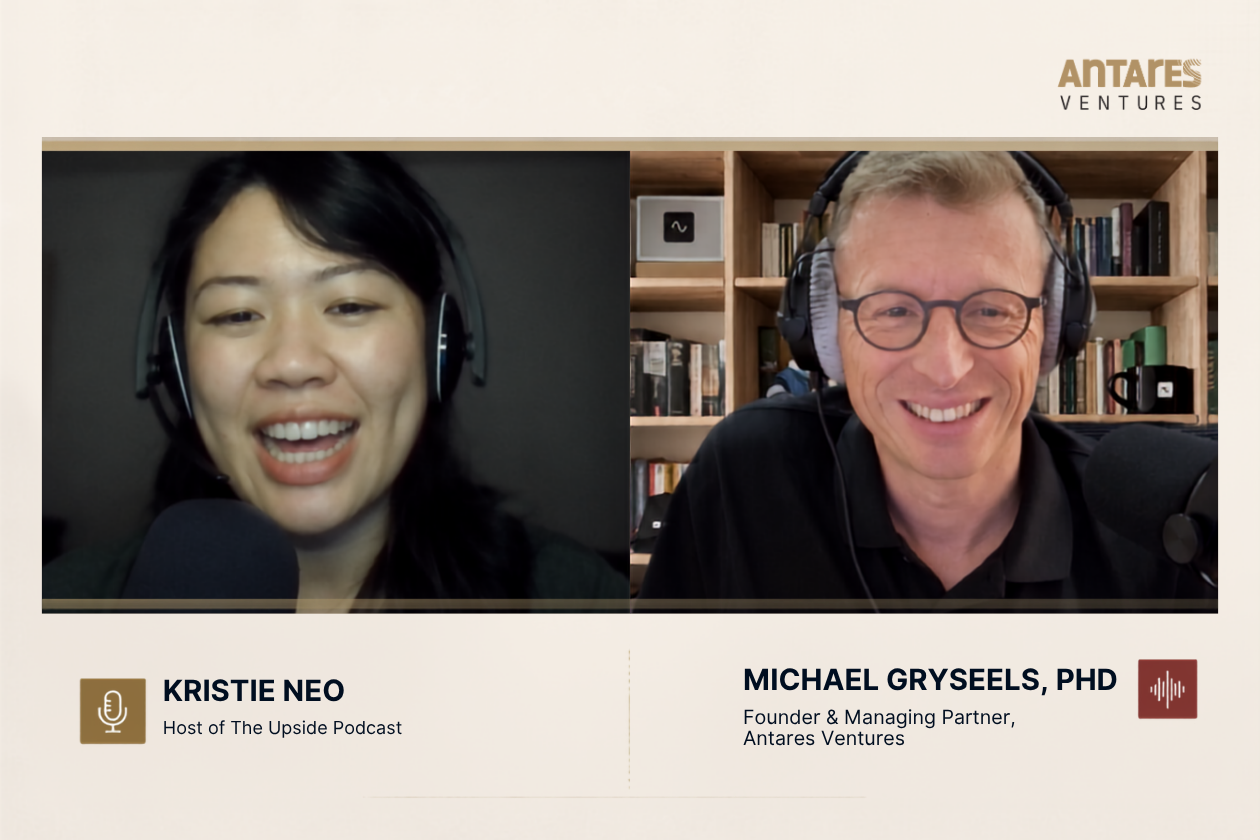
Our Founder & Managing Partner, Michael Gryseels, Ph.D. discussed why on a recent episode of The Upside Podcast with Kristie Neo. Energy plants, data centres, and factories are financed through capital stacks, not budgets someone has to carve out, so a technology that lifts an asset’s returns tends to get deployed fast.
Antares’ Asia-first value creation approach draws in part on Michael’s own years advising family groups and industrial corporates across Asia built on energy, manufacturing, and natural resources. That experience shapes how We underwrites deep tech today. We believe industrial groups’ appetite for new technology has grown out of decades spent running the physical businesses it’s meant to improve.
That’s what we look for in a deal: technology paired with people who already understand the asset it has to work inside, whether that’s an industrial plant or a semiconductor fab.
You can hear the full episode below on Spotify or YouTube. For more on how we underwrite deep tech, follow our insights on LinkedIn.
Prefer to read it in full? Below is the lightly edited transcript for deeper reading.
Kristie Neo: Hello and welcome to The Upside podcast. I am your host, Kristie, and today we have Michael, founder and managing partner of Antares Ventures. Antares is a Singapore-based VC fund focused on early-stage deep tech in Asia with a very specific focus on this cross-section of energy transition, advanced computing, industrial transformation, and infrastructure. Welcome, Michael.
Michael Gryseels: Thanks for having me, Kristie. I look forward to this.
Kristie Neo: Maybe if you can just take a step back. Antares Ventures—who is Antares? Take us back to the inception story. What led you guys to form this particular thesis and this very unique cross-section of energy transition and deep tech? Why did it make sense for you to build this particular thesis, and has that thesis evolved since the time that you guys started back in 2020?
Michael Gryseels: That’s quite a handful of questions. I’m going to share my personal story first; I think that will explain the rest. So, I started in the semiconductor day in the 90s. I was at some point in a clean room making lasers. I’ve kind of always been a tech geek nerd and fascinated about technology. I got headhunted into McKinsey when they were building up a high-tech practice and then spent some time in the US working with big-name tech companies.
I came to Asia about 15 years ago with my family and we fell in love with Asia here. Here in Asia, I pivoted from serving high-tech clients to helping any corporate in the region. There are lots of conglomerates that are very good at controlling their market but maybe less good at innovation. So, I launched a practice that was focused on innovation and venture building. That learned me a couple of things. One is that Asia is still, from a business point of view, very dominated by families—families that have a multi-decade horizon when they think about their business. At the same time, these families are quite curious and don’t necessarily have a “has to be invented here” type of approach.
I found myself working closely with the principals of some of the big Asian groups and advising them. Their kids had studied in the US and Silicon Valley, even before the days of AI, and they were thinking: what does it mean for our business? I think the roots of Antares go back from me being at McKinsey leading a practice on innovation and just having day-to-day conversations with executives and principals of groups here, which are by and large industrial groups. They made their money in natural resources, manufacturing, energy, or real estate.
Kristie Neo: When was it that you first came to Asia?
Michael Gryseels: It’s around 2011 or 2012, and we moved with the family in 2012. It was the first days of digital, with the first digital banks happening. But I worked with mining companies, agricultural companies, oil and gas companies, people in manufacturing, and retailers. I think the broader question was: how do we stay relevant in an age of technology?
I think that informed me that there was a role to be played between bridging innovation. Obviously, you have China, but I think the West has Silicon Valley, and even Europe with Oxford and Cambridge really have been spinning out technology innovation for a longer time. I felt there was a role to bridge global innovation with the markets here. I did that as a consultant first. I left McKinsey and I joined CP Group in Thailand—the largest conglomerate in Southeast Asia was my client. I became the Chief Innovation and Digital Officer for the entire group, advising the shareholder and the CEOs on how to think about technology. Gradually, this strengthened my belief that there’s a role for some platform that can bridge these worlds.
I started Antares in 2019. We were initially a syndicate. It was after I left McKinsey where I saw an opportunity to bring startups from North America, Europe, and some parts of Asia to Asia through my former clients. We syndicated with a few families; that’s how we got started. The idea for institutionalizing came after a couple of years. We had good returns; we had seven exits on 26 deals. Not only was it strategically relevant for my LPs, it was also earning money.
I felt that this was a strategy that very few people here in this part of the world were doing. I could see global deep tech funds happening in the US and in Europe—the likes of DCVC or Lux Capital in the US that are now multi-billion dollar funds—but I didn’t see anyone in Asia doing it, except for the government that was trying to foster deep tech innovation from its universities.
I set up Antares because I believe that there was a role for a platform, an institutional platform, that brought together investors and LPs from Asia, whether they are families or corporates, and brought global innovation to them. We did that through a venture capital model. What Antares is today is a deep-tech specialized investment platform. Our LPs are leading families and corporates from Asia. We have LPs from Japan, Korea, Southeast Asia, India, and Australia—all key markets except for China.
A financial return is the first thing, but we aim to add value beyond the financial return by giving our LPs exposure to cutting-edge technologies, explaining which ones make sense now, and helping them potentially synergize with our portfolio companies in their businesses. For a number of LPs, they want to invest direct, but they wouldn’t know how to source, let alone due diligence, an advanced semiconductor company or a robotics company.
At this point in time, we play in early-stage venture, Series A and Series B. We lead or co-lead most of the rounds and are very actively involved. Our real moat is our network amongst industrial families and corporates in Asia, which we leverage to help our portfolio companies land and expand in Asia.
Kristie Neo: Maybe if I can just take a pause there before we step into some of the comments you were making about family offices in Asia. You mentioned earlier that you spent a quite a sizable amount of time doing consulting for McKinsey and then moving into angel investing through syndicating some of these deals. What was that transition like for you? There’s a lot of market criticism particularly around consultants—that they sit on the outside on the periphery. It’s quite different to actually start doing deals and really have some skin in the game. How was that transition like for you? Were there any particular things that maybe you understood on a conceptual level that, when it came down to the actual execution or the scaling of a particular product or the go-to-market and the returns aspect of it, reflected a little bit differently for you as you were making that transition?
Michael Gryseels: So, I think, first of all, I’m not your typical McKinsey consultant. I haven’t done any MBA. I have a PhD in semiconductors. After I left McKinsey, I was CEO of CP Group’s digital business for five years. So, I’ve seen it as a technology nerd expert first and a business builder operator second. Even at McKinsey, I was leading a practice that was doing venture building. We built digital ventures and helped set up CVCs. We helped our clients actually in the early days when they didn’t have teams, so we helped them source and perform due diligence. I think I kind of learned it along the way.
Putting my own money in the game makes you a more responsible investor because you know that on some things you lose money and on some things you make money. It’s quite different if it’s your money versus if you just invest on behalf of others. I would say the one thing is that I’ve only done deep tech. I went back to universities and I just enjoyed speaking to those type of founders. At this point in time, I’ve done probably 40 deep tech deals. Even though some of them were done as an angel syndicate, I don’t think there’s many other VC principals that have had that longitudinal track record of doing deep tech in Asia for eight years.
Kristie Neo: You also mentioned that even until today, you guys are very actively talking to Asian conglomerates and family offices, and they also represent a very key part—not just for your fund, but actually for pretty much the entire market when it comes to deal-making here. What were some of the—I’m sure you have other family offices outside of Asia, or do you work with European ones?
Michael Gryseels: No. Our LP base is Asian. We have a few from North America, but 95% of our capital is from Asia—even more than that. We have an Asian LP base and we focus on raising capital from Asian LPs because that strengthens our platform. Our regional focus is to also raise from Asian families and family offices.
Kristie Neo: Fundraising, particularly in these days, is not easy.
Michael Gryseels: I think what you know—we’re a first-time fund from an institutional perspective—but what helps us is that Asian families have made their money in physical stuff. They have not made their money in software. So they actually relate much more to what we do than some of these very sophisticated software SaaS companies. They feel they can play a role in it. We do energy companies, like batteries and power equipment. We’ve done robots. We’ve done technologies for data centers.
A lot of these families have exposure to energy. If they’re not a consumer, then they’re either in mining, in oil and gas, or they have renewables. I find a lot of Asian families interested in the energy topic. What has happened in the last six months at the least has made the energy crisis even more acute. There’s a very broad interest in this part of the world around clean energy and new ways of generating energy. People have understood that you can make money in solar and wind, and they’re looking at what’s the next thing they can make money in. Is it batteries? Is it green fuels?
On the semiconductor side, I think we’re helped by public markets. Everyone—by the way, we saw memory being a bottleneck like I don’t know—I think I started sharing it with some of my LPs like 18 to 24 months ago. I’m not a trader, but I hope some of my LPs followed my advice. We detect some of these trends early and some LPs want to get exposure to semiconductors—the physical side of AI rather than the software side of AI, which I think is overvalued. But it’s complicated. It’s very complicated in semiconductors to figure out even what the companies are doing, how they’ll make money, and in what timeframe they’ll make money.
Then on the industrial side, we have a number of industrial families. So, when we talk about things like robots, advanced process engineering, or new lower-carbon ways of making metals, cement, and chemicals, that’s kind of core to their business. I think the thematics that we invest in are very relatable to these families. That helps us. It helps that there’s not many of us here, so we get the audience. We can credibly say it’s not just me, but amongst my partners and I, we have touched a lot of deals and can show successes. A lot of LPs appreciate that I have a global background, we have a global advisory board, and we have venture partners in the US and Europe. They want to know what’s happening there and we’re able to bring first-hand stories from Silicon Valley and Europe in terms of new computing and other technologies. I think that is what gives us the attention.
Kristie Neo: Are these Asian families still as active when it comes to doing directs in the space today? I’ll say for a few reasons. I think there was a wave of a lot of activity from family offices over the last five to seven years with SaaS, and some of them got burned, so I have heard of a bit of a retreat. But at the same time, depending on what the core business is—as you say, if their core business is oil and gas—how is that reflecting in the way that they are choosing to participate in deals or co-invest in deals and do due diligence on deals? For you as a GP, you’re also positioning yourself as a partner to a lot of these guys.
Michael Gryseels: We started by syndicating; syndicating has been in our blood. For what we do, again, because all of our companies are technically complex and because we source deals from all parts of the world, they look at us as a platform they can co-invest in. They can rely on our sourcing, on our due diligence, and our monitoring of the companies, but they can enjoy part of the upside.
In some cases, they want to see synergies, but in other cases, they want to just have direct investment as part of their asset allocation. For example, semiconductor is very hot right now. I’m having a lot of LP conversations around semiconductors; they want to get exposure to this. You can either do it through public markets where most of the public companies have had a spike in valuations, so the question is how much higher can that go? But on the early-stage side in semiconductor, we get in at quite reasonable valuations and we’re able to explain why those companies in a 3-year timeframe could be very successful. It’s a way for them to get exposure to the sectors that are driving today’s economy, whether it’s AI or the energy side, but with a partner that helps them to de-risk. We’re not forcing them to co-invest—it’s completely optional—but I would say the majority of our LPs invest in our fund to get access to the co-investments.
Kristie Neo: One of the challenges for private markets as a whole is they tend to get compared to public markets which have done phenomenally well. I don’t know if that’s something that you get a bit of pushback on as well.
Michael Gryseels: There would be some people that say—which I think is a bit simplistic—”I’m making such a high return in my public market portfolio, why should I go private?” I think the more sophisticated investors are nervous on valuations. There is a question around the whole AI trade and how much more that can go up. The semiconductor public trade, how much more can that go up?
Objectively speaking, the valuations that we’re getting for our companies are far more attractive than what you can get in the public markets. For the more sophisticated family offices and LPs, they get it. You just look at SpaceX; a lot of these companies stay private for a long time. By the time you get public market exposure, it’s priced in. In the domains that we’re in, private is a way to ride more of the upside. That’s an argument that I think I’m making and I think it’s generally accepted.
Kristie Neo: Have you seen any inflation in specific sectors in terms of valuations, especially those that have a bit of exposure to AI here in Asia? Do you think there’s still a big disparity between what you’re seeing here in Asia versus maybe some of what you’ve seen in Europe?
Michael Gryseels: For sure, in the US, a number of these topics have become hot. I think in Asia, there are far fewer investors that understand these sectors and are able to underwrite them. For example, in semiconductors, we are now looking in Taiwan, Korea, and Japan. You’d be surprised; there are very few investors in those markets versus the universe of companies that you have there. I can count the number of VCs that credibly understand semiconductors at the technical level—taking out China—at maybe less than 10.
It leads to less competition and less discovery. US VCs won’t go into Japan, but Japan has historically had an edge in electronics and advanced engineering. Korea is now on everyone’s radar, but it’s hard to get into those markets. We have one of our advisors who was formerly with Samsung Ventures; he was leading Samsung Ventures. I have a Japanese partner. We’re able to move with Mandarin-speaking venture partners. We’re able to move in markets where perhaps the Western VCs just won’t get access and where, from a local point of view, there’s just not many players like us. That is the opportunity. That being said, we do look at North America and Europe. Probably half of our pipeline is Asia and half is outside. Then it depends a bit on the topic, valuation, and strengths. I think East Asia semiconductors have lots of opportunity in my view.
Kristie Neo: What about other sectors? To be in line with the Asia story, especially in this cross-section you mentioned about energy transition and deep tech, are there other areas that you think Asia has the potential to be able to corner as a market? From your vantage point, where do you see the bright spots that maybe when you speak to other LPs or investors, they may not necessarily see so clearly or they may even have misconceptions on?
Michael Gryseels: You asked me actually earlier and I didn’t fully answer that: how our thesis has evolved. Our thesis has evolved in a few ways. Number one is our view of the world: we’re in a capex supercycle. We’re rebuilding the world at a scale and a pace we’ve never known before. That’s happening in energy, that’s happening in compute, and that’s happening in industry. The gravity is in Asia.
The reason we picked these three thematics: Clean energy—the world is now spending 2.5 trillion dollars in capex on clean energy. That’s more than double than what we’re spending on oil and gas. Two-thirds of that from a capacity point of view is in Asia. It used to be China, but now it’s shifting; it’s happening in India. I’m very excited about India moving very fast on decarbonizing its economy. The biggest solar plant in the world is in Ahmedabad, that is in Gujarat, India. It’s not in China.
The second thematic is data centers. If you think about the value chain—OpenAI, Anthropic, Grok, and all of those guys are raising a lot of capital—we’ve analyzed where the capital goes. First of all, more than 70% goes to data centers. More than 70% of data center money goes to semiconductors. Nvidia may design the chips, but who makes the chips? It’s TSMC. It’s all flowing back. If you look at the economic value at the manufacturing base of semiconductors, 70% is in Asia.
Then manufacturing—pick your industry—between 60% and 80% is in Asia. North America and Europe want to regain back manufacturing, and they’re trying through tariffs and so on, but at the end of the day, Asia has just built up capabilities and cost-competitiveness in manufacturing. That’s obviously a China story, but also increasingly Southeast Asia—Vietnam, Thailand, and Malaysia have a manufacturing base. Even Indonesia is building up capabilities in electronics and in cars, batteries. East Asia—Korea, Taiwan, Japan—handles anything more advanced.
The story across these three thematics is that the world is building things. The number we track is how much capex is spent and how much infrastructure is built across these sectors. The number today is 6 trillion dollars per year. The same number five years ago was 2 trillion. We went from 2 trillion to 6 trillion, and we think that the majority of the economic value added is captured in Asia because the things are built here. That’s why we picked these three thematics.
The other thing that we’ve learned as the thesis evolved is something quite fundamental about scaling deep tech. At the end of the day, the pace of a B2B company is driven by how big the budget is from the people procuring you. If I’m selling software, I need to convince a CEO who has a budget—let’s say the CEO has a budget of 100 million—and if I want to sell software for a million, you have to carve out a million somewhere. If I’m selling technology for a data center, there’s no such thing as budgets. Data centers are project-financed. There’s a whole capital stack. When AWS builds a data center, they finance 10%? Most of it is financed by project equity and project debt.
The scale of budgets available and the pace of deployment is much faster in anything that is infrastructure. Energy, data centers, manufacturing plants—all of that is project-financed. What we need to prove is that our technologies can help the asset IRR. One question we have in our Investment Committee is: how does our technology improve the economics for the asset owner? We think if it improves their economics even by 100 basis points, they’ll be deployed very rapidly.
Kristie Neo: Where do you source for these deals? Where do these companies come from? Are they mostly spin-offs or do you get a lot of them from the universities? One of the criticisms is the challenge of bridging IP that comes out of some of our universities to commercial applications. That tends to be one of the hurdles, at least in Asia. I know in Singapore it is one of the key hurdles. In Japan and Korea, it maybe looks a little different because you have the chaebols and CVCs. What has that experience been so far?
Michael Gryseels: Let me break it down. In our companies, there is always a science-based innovation. AI has helped to accelerate science, but it typically takes time. It is not like an incubator you and I go into and we come out with a startup. Most of our companies have roots in universities, so they’ve been either spin-offs or started by people that have been doing research in the domain before. We typically don’t invest at the stage where they are just spinning out; we’re more Series A investors. The companies at the time we invest are typically between 5 and 8 years old. They’ve typically raised around 10 million dollars in equity already. They’ve typically raised the same or more in non-dilutive funding. They will have between 20 and 50 employees depending on where they are.
Secondly, regarding location: it depends on the topic. In semiconductors, we are very focused on East Asia now and pockets in Europe like Belgium and the Netherlands. I’m Belgian, so I know that ecosystem quite well. Also the UK. On the energy side, we’ve been very fascinated by what is happening in India because India has such a progressive government. Relative to growth, China is ahead, but the relative growth of renewables is the fastest in India. There is a lot of innovation in energy technology in India. On the industrial side, it depends. If it is materials, Singapore is very strong. On the computing side, Australia is very strong in quantum computing.
We have defined 33 “frontier industries,” which are the industries of the future. For each of them, we map where these are likely going to happen. So, we’re global, but then if you look at a topical level, we’ll look mostly at Japan, Korea, India, or Europe.
Thirdly, regarding university IP: I actually think Singapore has done a fairly good job at streamlining how IP gets out of universities and how that gets commercialized. In some countries, like the UK, it is very notable where university professors will keep 30% or 40% of the equity, or the university itself will keep a lot of the equity. Then you get a company which is non-investable at some point. I think Singapore has done a good job at that. It depends a bit on the maturity of the ecosystem. We like IP that comes from universities, but we don’t like it if the universities hold on to too much of that IP because then the companies just are not investable.
Kristie Neo: When you say they hold on to the IP…
Michael Gryseels: Have you heard of GRIP (Graduate Research Innovation Programme)? GRIP was started in the US—I think the Singapore government, by nationalizing GRIP—and now GRIP is done through all universities—has done a really good job. In GRIP, the companies have zero equity; the university holds zero equity in those companies. The only IP is handled through a royalty agreement, which is fairly founder-friendly and company-friendly. In a couple of other markets, it depends on the dynamics with the university.
Kristie Neo: Are there any other markets in Asia that you think are a bit more progressive for building entrepreneurs or helping them to step out?
Michael Gryseels: Australia. University of New South Wales and Victoria—I think Australia has done a pretty good job as well.
Kristie Neo: What about in terms of talent in your portfolio? How much do you deploy in Asia and how much do you deploy globally? I guess you do have to have some sort of Asian angle to your particular fund.
Michael Gryseels: Historically, we’ve deployed about two-thirds in Asia and one-third outside. Going forward, we’re obviously biased toward Asia. It’s easier to scale a company that is based in Asia across Asian markets. But for a number of topics—nuclear or very advanced computing stuff—it may not be in Asia yet. There are a number of topics for which we still look outside in the US and Europe.
Increasingly, we think the ecosystem and the gravity are here. That starts with government policy, universities, etc. It will take some years for that to fully mature and be at the same level of maturity as North America and Europe, but I am actually very optimistic on deep tech coming out of Asia. It’s not just a Singapore story. I’m very excited about what is happening in India. The Indian deep tech ecosystem and the government have also been quite supportive of that, and obviously, you have massive talent. Japan and Korea just have a historic base which is a strength, and the benefit of Japanese and Korean startups is that they have these industrial groups that they can collaborate with quite easily. Taiwan has historic semiconductor capabilities. For Australia, in a number of domains like quantum, they have done quite well.
I think Asia has a lot of promise. The markets are here and the capabilities are here. What is missing is people like us. There should be more people like us. The generalist VC will find it very hard to underwrite the type of company that we invest in. We’ve invested in an electric plane. We led the Series B of a company called ePlane. They make vertical takeoff and landing aircraft, or “air taxis” as they’re commonly known. It’s a highly sophisticated engineering project. The plane itself has more than 10,000 different components. You have regulation. We invested when they didn’t have a full-size prototype and were years away from revenue.
It is not your average VC deal. We need more people that have the capabilities of assessing a very highly complex technical company with a highly technical product and the ability to judge how fast that can go to market and then how much they can scale. That’s very different from software where you have revenue more or less on day one and you look at CAC, user acquisition, growth metrics, and burn ratio, and you have an idea whether the company is good or not. In a software company, you hardly do technical due diligence. What we do requires specialized investors. There are only a handful of us in Asia now. We hope to be one of the leading ones, particularly with a regional platform. Most of our competitors are single-market focused. The fact that we’ve been able to build an LP base from Japan and Korea to Southeast Asia, India, and Australia gives us a platform where we can help companies across Asia. We think that will help our companies to scale more effectively than VCs that are more single-market focused.
Kristie Neo: What about in terms of exit opportunities for your own portfolio? For the same reasons you mentioned, obviously, you don’t have enough investors who actually understand this particular space, which means the pool of potential investors and acquirers is also somewhat limited. Do you have to measure or manage expectations for exit timelines for some of these companies?
Michael Gryseels: So, we’ve invested since 2019. Before the fund, we did 26 deals and we have seven exits. That’s on an average cohort that is six to eight years old. I think that’s quite different in deep tech. What happens in deep tech is that there’s corporate acquirers that want to buy the companies for their IP. Seven out of seven exits were corporate money. Seven out of seven were bought not for the revenue, but for the IP, the product, and the capabilities of the team.
We see an earlier exit route in deep tech, which is counterintuitive, because you have big corporates that have come to realize that internal R&D is not as productive as just buying a company that has built it already and has a world-class team. Again, that’s why we’re present in Japan and Korea, where we think the big industrial groups—the Mitsubishis, Mitsuis, and Sumitomos of this world, the Hyundais—are acquisitive. They have a lot of cash and they have the capability and a proven record of acquiring such companies. Then we have connections with corporates in Europe and the US as well.
I’ve been positively surprised by some listings. There have even been some listings on the SGX. Maybe I won’t mention the names here, but there have been listings of semiconductor companies on Catalyst—of pre-revenue semiconductor deep tech companies—that have done quite well. We’ll need to see more of them to get broad market interest, but Hong Kong, Japan, Korea, and India all have appreciation for this type of tech. I think a number of these companies could actually list even while their revenue may not be fully mature.
At the early stage, where you don’t have the revenue, you have very few specialized investors like us. Once a company reaches Series B or Series C, you have corporate investors, you have sovereign wealth funds—Temasek has actually done quite a lot of deep tech investments. Khazanah has quite some semiconductor investments in their portfolio. The sovereigns, because they see an angle of strengthening national economies, want to make bets on these types of companies.
We are not betting on any one of these three routes. I would say corporate M&A is the one that is closest to our heart because we have this corporate approach. For all of our companies in the Investment Committee, when a deal gets discussed, we always ask the sponsor: who is going to acquire this company? Which corporates? And do we know one of them? We need to know at least one of them. We introduce those kinds of corporates early on. I always say to my founders: don’t think that suddenly we are going to hire a banker and sell the company. Your acquirer is likely a corporate that has been working with you for years already. By introducing corporates early, we build the relationships, the intimacy, and the credibility. They might just do a pilot project first, and then they might do a co-investment later on, and then at some point, they acquire. That is a recipe which we have done many times.
On the listings, again, I am cautious, but I can see across markets more appetite because public markets have done well—more appetite for the type of companies that we invest in. Secondaries through sovereigns are also an exit option for some of our companies.
Kristie Neo: Are you seeing any kind of interesting cross-border M&A interest, especially within the region? Broadly, there seems to be increasing cross-border interest.
Michael Gryseels: We speak to Japanese corporates all the time. Japan is going, in my view, through an industrial renaissance. They have bold government policy and they have two big programs: DX and GX. GX is about green; DX is about digital. All of the corporates are looking at what they can acquire. Japanese and Korean corporates are definitely looking at other parts of Asia, not just the US. In fact, most of these corporates have relationships with US VCs, but more and more now, because of what is happening globally, they want to diversify away from buying things in the US.
Kristie Neo: What kind of exit multiples have you seen for some of these M&A offers? And in terms of the minimum check size—it seems like they do acquire very early because some are pre-revenue, but they do need to be at a particular size before they start getting interested in you.
Michael Gryseels: I would say anywhere from 50 to 500 million. Fifty million when they are really pre-revenue; 500 million when they have some revenue. Typically, what these corporates will look at is not the revenue, but the blue-chip logos. Which customers does this startup have? That gives them more credibility and valuation.
The other thing is that the world is moving in very interesting ways, but I actually think the hyperscalers, which themselves have massive M&A capacity, are going upstream. We have seen Google, Meta, and Microsoft have a keen interest to go into energy because they know that their bottleneck is not just the software—it is the chips and it is the energy. Our companies, without disclosing individual details, are all talking to these guys as potential investors.
Kristie Neo: Another area that has shifted the conversation around energy transition is the war and oil prices and inflation. Even I thought this was going to wrap up by now, but it doesn’t look like that is going to be the case. I think that’s always going to…
Michael Gryseels: …in without a plan.
Kristie Neo: The whole energy transition conversation obviously has shifted quite a lot as a result of the war. What would you say would be the most distinctive shift for you, especially in your fundraising and among your portfolio companies, and how do you see this unfolding over the next 6 to 12 months?
Michael Gryseels: Despite the war being a regretful thing, there is no country in Asia today that is not worried about energy resilience. Asia, by and large, does not have fossil fuel reserves. We did an analysis, and if you look at the commodities that went out of harm’s way—between 60% and 80% went to Asia—fertilizers, sulfur, LPG, and refined products. Singapore manages those resilience scenarios well, but countries like the Philippines, Indonesia, Thailand, and Vietnam have run out of diesel in some places. I was told by a friend in the Philippines that electric vehicles are sold out for the next 12 months. You have to wait because that is the only way you can get around.
What this has led to is that both at the public level and the private level, organizations have felt the pain. I was told by a mining company that one of their sites ran out of diesel, so they had to stop operating. I know a company in PVC that ran out of chemicals. Another company had to shut down their plant. People have lost money and they are not going to be burning it a second time. We are having a lot of conversations asking: are there different ways of producing it? Can we produce this without oil? There is a discussion around biofuels and we have some technologies for that.
There is a discussion around electrification. For example, we have a company that electrifies heat. So instead of generating your heat through gas or through diesel, you generate the heat through electricity. The whole topic of industrial decarbonization and energy transition is now driven by a very different agenda, which is energy resilience if the next thing like this happens—and this thing isn’t even over.
I think Asia will lead the world on energy transition and decarbonization. It isn’t just about commitments for net zero—it is a matter of survival for some countries. The Philippines has only one single refinery; 90% of their fuel is imported. Cambodia has no refineries. Even Indonesia does not refine most of its own oil even though they have oil. But what Southeast Asia does have is a lot of biomass, so there are biofuel options. For renewables, there is a lot of land, so you can build solar and wind.
I think this accelerates the whole transition by a big factor, and it is not going to slow down. If tomorrow’s fuel is there, people in the Philippines are not going to say, “Oh, we are not going to buy an EV, we are going to buy a fuel car.” They are going to buy an EV. Across transport, industry, and power generation, whatever forecasts there were on clean energy or alternatives to oil and gas, those will accelerate. For us, we are backing those technologies, so they are more relevant than before. There is more urgency and faster adoption, which is good for our companies. There is also more interest from fund backers because we have a sense of what can be deployed quickly.
Kristie Neo: I think there is also a rising interest around this idea of sovereignty as a national agenda—things like cybersecurity, defense, the rush to secure supply chains, and data protection. Do you see that filtering into the interest areas that your LPs and investor partners are looking into? Also, regarding reporting and auditing for some of these areas—this is where geopolitics starts to creep in—have you seen that playing into some of the areas you guys look into, especially semiconductors? They are along the borderline of things that are geopolitically sensitive.
Michael Gryseels: It plays out in different ways. Take commodities and a country like India. India’s biggest constituent from a voter perspective are farmers. Farming is extremely subsidized in India. India has been running out of fertilizer because it needs to import it. So now there has been a policy and private investment toward generating fertilizer that does not come from the Middle East—things like green hydrogen and green ammonia. We have a green hydrogen company in India which is seeing massive interest that wasn’t even there 6 months ago.
On the compute side and the infrastructure side, people are worried. We don’t invest in China, so a lot of our companies are non-Chinese companies. One of their value propositions is sovereignty. We have a company that makes a transformer—it is historically boring to try to transform from high voltage to low voltage, and this particular company does it through electronics. There is no US hyperscaler that would buy a Chinese transformer, but they would buy it from our company. So it creates certain opportunities that wouldn’t be there before.
On the security side, pre-fund we did an investment in a company that protects physical assets via cybersecurity. Instead of protecting software, you protect ports, refineries, and desalination plants. Guess what has happened in the Middle East? Not only rockets and drones, but there have been massive cyberattacks on physical infrastructure. And so yeah, this is now front and center again. As a fund, we don’t focus on defense, but we see security in an industrial context as a big topic. How do you protect your port or your airport? Those are the less visible attacks that can put down an economy. If you look at the war, it is about economic leverage.
Kristie Neo: Maybe just one last question around one particular sector that you and your team have been keeping your eye on in Asia that you think has a lot of potential—something you are spending a lot of time on that is under-covered and deservedly the most exciting thing Asia could offer?
Michael Gryseels: We are very bullish on semiconductors in Asia. We think that there is a lot of good IP and innovation in Asia which has not been discovered because there are very few specialized investors like us with the expertise to discover those types of deals. On top of that, startups in semiconductors are closer to the actual value chain, which is also in Asia. We are looking at topics like silicon photonics, optical interconnects, new chip architectures, and new ways of packaging and integration of chips. There is both the IP and the talent.
Even in Singapore and Malaysia, there is a pretty strong and growing semiconductor industry. The non-China semiconductor industry is particularly going to benefit a lot because the West will not buy Chinese semiconductors. I am very bullish on that, and I think it is not sufficiently covered and understood. Everyone is focused on the US because the center of AI is around the US, but the chips are made here.
Kristie Neo: How do you guys do due diligence on some of these companies? You seem to be covering a very vast segment of sectors that are incredibly technical. How is your team structured and how do you hire for the people to do the right due diligence on these deals?
Michael Gryseels: You are totally right that it is technical. You cannot hire all of the competences inside the team. So, we work a lot with experts. We have a whole roster of industry and technical experts. We have former semiconductor CEOs; as I said, one of our advisors used to lead Samsung Ventures. Across the history of the firm, we have invested in close to 40 companies and my partners have invested in another 20. We have a lot of CTOs that we can call, and our CTOs themselves have a network of other people. It is a very network-driven approach to identifying experts. Our team brings the research on what the problem is—we connect with the corporates to understand the problems in data centers today—and then we find the companies. Once it gets to technical due diligence, we will always involve external experts by having them closely involved with the firm.
Kristie Neo: I think that is all the time we have for today, but thank you so much for joining me.
Michael Gryseels: No, thank you for having me, Kristie. Thanks for the questions.
Kristie Neo: See you around soon. we will see you soon.
Michael Gryseels: See you soon.
—
If you are investing in or building science-driven technologies that measurably improve system performance across Asia, we welcome the opportunity to connect.